₹500 a Month SIP: What It Could Become in 10, 20, and 30 Years
Written by Ashish Suryakant Pawar
14 Oct 2026 • 6 minutes read


At an assumed annual return of 11%, a ₹500 monthly SIP could potentially grow to approximately ₹1 lakh in 10 years, ₹4.30 lakh in 20 years, and ₹14 lakh in 30 years.
These figures are only illustrations. Actual returns are market-linked and may vary.
The SIP full form is Systematic Investment Plan. It is a method of “gradual investing” in which a pre-determined sum of money is invested periodically (say every month or quarter), regardless of market conditions.
Want to know how much you can accumulate with a ₹500 monthly SIP?
Read this article to check out the potential maturity values under different assumed rates of return. But first, let’s look at the standard formula used to calculate the maturity value of a SIP.
Table of Content

How to Determine the Maturity Value of a SIP?
For a monthly SIP, the maturity value depends on three primary factors:
- The amount invested each month
- The expected rate of return, and
- The investment period.
The standard formula used to estimate the future value of a monthly SIP is:
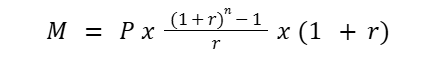
Where:
- M = Maturity value of the SIP
- P = Monthly SIP amount. For example, ₹500
- r = Monthly rate of return. For example, if the assumed annual return is 12%, then r = 1%
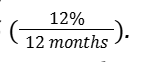
- n = Total number of monthly instalments. For example, for a 5-year SIP, n = 5 × 12 = 60 months
Additionally, the factor “(1 + r)” adjusts the calculation for investments made at the beginning of each month (assuming the SIP is treated as an annuity due).
Want to Go Beyond SIP Calculations? Read more educational blogs to learn about SIPs, CAGR, XIRR, compounding, taxation, and other concepts. |
What Could You Have Potentially Accumulated by Investing ₹500 a Month for “10 Years”?
Let’s assume you had invested ₹500 every month for 10 years in a mutual fund scheme following the benchmark of Nifty 50. Now, your total investment would have been ₹60,000 (₹500 × 120 months).
Depending on the assumed annual rate of return, this investment could have potentially grown to the following amounts:
Assumed Annual Return | Total Investment | Approximate Maturity Value |
8% | ₹60,000 | ₹90,000 |
9% | ₹60,000 | ₹95,000 |
10% | ₹60,000 | ₹1 lakh |
11% | ₹60,000 | ₹1.05 lakhs |
What Could You Have Potentially Accumulated by Investing ₹500 a Month for “20 Years”?
If you had invested ₹500 every month through a SIP for 20 years, your total investment would have been ₹1,20,000 (₹500 × 240 months). Depending on the assumed annual rate of return, your ₹500 per month SIP could have potentially grown to the following amounts:
Assumed Annual Return | Total Investment | Potential Maturity Value |
8% | ₹1,20,000 | ₹2.90 lakhs |
9% | ₹1,20,000 | ₹3.30 lakhs |
10% | ₹1,20,000 | ₹3.75 lakhs |
11% | ₹1,20,000 | ₹4.30 lakhs |
What Could You Have Potentially Accumulated by Investing ₹500 a Month for “30 Years”?
If you had invested ₹500 every month through a SIP for 30 years, your total investment would have been ₹1,80,000 (₹500 × 360 months). Depending on the assumed annual rate of return, this investment could have potentially grown to:
Assumed Annual Return | Total Investment | Potential Maturity Value |
8% | ₹1,80,000 | ₹7.40 lakhs |
9% | ₹1,80,000 | ₹9.10 lakhs |
10% | ₹1,80,000 | ₹11.30 lakhs |
11% | ₹1,80,000 | ₹14 lakhs |
Disclaimer: The performance data presented herein are not verified by Past Risk and Return Verification Agency (PaRRVA) or any other agency recognized by SEBI for this purpose. The performance data presented herein may not be comparable to performance data of any other IA/ RA. Computation of the performance may vary across the industry.
Users are requested to apply their due diligence before making investment decisions on the basis of the given past performance data. Past performance is no guarantee of future results. Investment in securities is subject to market risk. Registration with SEBI or enlistment with IAASB or RAASB (as the case may be) is not a guarantee or assurance of future returns.
Conclusion
So, now you know what a ₹500 per month SIP could potentially accumulate at assumed annual return rates of 8%, 9%, 10%, and 11%. If we were to revise, SIPs are a way of gradual investing, where you invest a fixed amount at regular intervals over a period of time.
If you had invested ₹500 per month for 10, 20, or 30 years, your total investment would have been ₹60,000, ₹1,20,000, and ₹1,80,000, respectively. At an assumed 11% annual return, these amounts could have potentially grown to approximately ₹1.05 lakhs, ₹4.30 lakhs, and ₹14 lakhs, respectively.
However, these figures are only educational and illustrative, based on assumed rates of return. Actual mutual fund returns are market-linked and may vary.
For more information, you can visit www.tatamutualfund.com/deshkarenivesh. The Investor Service Centre of Tata Asset Management Pvt. Ltd. is located at Mulla House, Ground Floor, 51, M.G. Road, Near Flora Fountain, Mumbai – 400 001, Maharashtra. The office hours are Monday to Friday, 9:00 AM to 5:30 PM. For assistance, you can also call (022) 6282 7777 from Monday to Saturday, 9:00 AM to 5:30 PM, or email service@tataamc.com
₹500 Monthly SIP FAQs
1. Does investing for a longer period always result in better returns?
A longer investment period may give the invested money more time to “compound”, which can increase the potential maturity value. However, a longer period does not guarantee better returns as a mutual fund's performance depends on market conditions.
2. Can I increase my ₹500 monthly SIP amount later?
An investor can increase the amount of an existing SIP following these two methods:
- Modify the existing SIP: Log in to your mutual fund platform, select the existing SIP, and check whether an option such as “Modify SIP” or “Change SIP Amount” is available. You can enter the new monthly amount and confirm the change. Some AMCs may instead require a SIP modification request.
- Use a SIP Top-Up: If available, you can opt to increase the SIP by a fixed amount or percentage at predetermined intervals, such as every six or 12 months. This allows the SIP amount to rise automatically over time.
Note: The exact process depends on the mutual fund or platform through which the SIP was registered.
3. How to calculate my potential SIP returns without manual calculations?
You may use an online SIP calculator. Generally, you are required to make some basic inputs, such as:
- The monthly investment amount
- Expected rate of return, and
- Investment period
The SIP calculator can then instantly estimate the total investment, potential returns, and maturity value based on your inputs.
Disclaimer:
An Investor Education and Awareness Initiative by Tata Mutual Fund.
To know more about KYC documentation requirements and procedure for change of address, phone number, bank details, etc., please visit: https://www.tatamutualfund.com/deshkarenivesh
Please deal only with registered Mutual Funds, details of which can be verified on the SEBI website under ‘Intermediaries / Market infrastructure institutions.’
All complaints regarding Tata Mutual Fund may be directed to service@tataamc.com and/or https://scores.sebi.gov.in/ (SEBI SCORES portal) and/or https://smartodr.in/login
Nomination is advisable for all folios opened by an individual, especially with sole holding, as it facilitates an easy transmission process.
This communication is a part of the investor education and awareness initiative of Tata Mutual Fund.
*Mutual Fund Investments are subject to market risks, please read all scheme related documents carefully.
Author Bio
Ashish Suryakant Pawar
Loading Form...
Loading Similar Blogs...