₹2,000 a Month SIP: What It Could Build Over 15, 20, and 25 Years
Written by Ashish Suryakant Pawar
28 Oct 2026 • 6 minutes read
If you had started a ₹2,000 monthly SIP in a mutual fund scheme tracking the Nifty 50 benchmark, your investment could have potentially grown to approximately ₹9 lakh* in 15 years, ₹17 lakh* in 20 years, or ₹31 lakh* in 25 years, assuming an annual return of 11%.
*These figures are only illustrative estimates.
A Systematic Investment Plan (SIP) allows an investor to invest a fixed amount, such as ₹2,000, in a mutual fund every month. Each instalment buys mutual fund units at the prevailing Net Asset Value (NAV).
Consequently,
- When the NAV is low, the instalment may buy more units.
- Whereas, when the NAV is high, it may buy fewer units.
This is known as “rupee-cost averaging”. The total number of units accumulated depends on the NAV at which each instalment is invested. But how much could you potentially accumulate by investing ₹2,000 per month over 15, 20, or 25 years?
Read this article to learn how the potential value of an SIP investment is calculated and explore the estimated accumulated amounts over these investment periods at different assumed rates of return.
Table of Content

How to Calculate the Potential Value of an SIP Investment?
The future value (FV) formula estimates how much the SIP investment may grow over a given period, based on an assumed rate of return. Mathematically, it can be presented as follows:
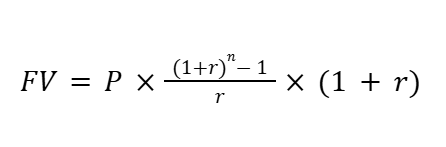
Where,
- “P” is the monthly SIP amount (say ₹2,000).
- “r” is the expected monthly rate of return (annual expected return divided by 12).
- “n” is the total number of monthly instalments.
Furthermore, the term
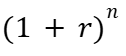
accounts for the effect of “compounding” over the investment period, while subtracting 1 and dividing by r calculates the accumulated value of the monthly contributions.
The final term,
, assumes that each instalment is invested at the beginning of the month. Such an assumption gives it one additional month to earn returns.
Conversely, if instalments are assumed to be invested at the end of each month, this final term is omitted.
Want to learn more mutual fund concepts? Keep reading more educational blogs on compounding, market returns, long-term wealth creation, how SIPs work, and similar topics. |
What Could You Have Potentially Accumulated by Investing ₹2,000 Per Month for 15 Years?
Suppose you had started a ₹2,000 monthly SIP in a mutual fund scheme tracking the Nifty 50 benchmark for 15 years. Over this period, the total amount invested would have been ₹3,60,000 (₹2,000 per month x 12 months x 15 years).
Depending on the assumed annual rate of return, the investment could have potentially grown to the following amounts:
Assumed Annual Rate of Return | Total Investment | Potential Accumulated Amount |
8% | ₹3,60,000 | ₹6.5 lakhs |
9% | ₹3,60,000 | ₹7 lakhs |
10% | ₹3,60,000 | ₹8 lakhs |
11% | ₹3,60,000 | ₹9 lakhs |
What Could You Have Potentially Accumulated by Investing ₹2,000 Per Month for 20 Years?
Suppose you had started a ₹2,000 SIP in a mutual fund scheme tracking the Nifty 50 benchmark for 20 years. Over this period, the total amount invested would have been ₹4,80,000 (₹2,000 per month x 12 months x 20 years).
Now, depending on the assumed annual rate of return, this investment could have potentially grown to the following amounts:
Assumed Annual Rate of Return | Total Investment | Potential Accumulated Amount |
8% | ₹4,80,000 | ₹11 lakhs |
9% | ₹4,80,000 | ₹13 lakhs |
10% | ₹4,80,000 | ₹15 lakhs |
11% | ₹4,80,000 | ₹17 lakhs |
What Could You Have Potentially Accumulated by Investing ₹2,000 Per Month for 25 Years?
Suppose you had invested ₹2,000 per month in a mutual fund scheme tracking the Nifty 50 benchmark for 25 years. Over this period, the total amount invested would have been ₹6,00,000 (₹2,000 per month x 12 months x 25 years). Depending on the assumed annual rate of return, this investment could have potentially grown to the following amounts:
Assumed Annual Rate of Return | Total Investment | Potential Accumulated Amount |
8% | ₹6,00,000 | ₹19 lakhs |
9% | ₹6,00,000 | ₹22 lakhs |
10% | ₹6,00,000 | ₹26 lakhs |
11% | ₹6,00,000 | ₹31 lakhs |
Disclaimer: The performance data presented herein are not verified by Past Risk and
Return Verification Agency (PaRRVA) or any other agency recognized by
SEBI for this purpose. The performance data presented herein may not be
comparable to performance data of any other IA/ RA. Computation of the
performance may vary across the industry. Users are requested to apply
their due diligence before making investment decisions on the basis of the
given past performance data. Past performance is no guarantee of future
results. Investment in securities is subject to market risk. Registration with
SEBI or enlistment with IAASB or RAASB (as the case may be) is not a
guarantee or assurance of future returns.
Conclusion
So, now you know how much you could have potentially accumulated by starting a ₹2,000 monthly SIP 15, 20, or 25 years ago. To recap, a Systematic Investment Plan (SIP) is a method of investing a fixed amount at regular intervals, such as monthly or quarterly, irrespective of market conditions.
If you had started a ₹2,000 SIP in a mutual fund scheme tracking the Nifty 50 benchmark, your investment could have potentially grown to approximately:
- ₹9 lakh in 15 years
- ₹17 lakh in 20 years, or
- ₹31 lakh in 25 years, assuming an annual return of 11%.
Note that these figures are illustrative estimates. Actual returns depend on market performance and may differ from the assumed rate. The calculations only demonstrate how investment duration and compounding can influence the potential value of an SIP investment.
For more information, you can visit www.tatamutualfund.com/deshkarenivesh. The Investor Service Centre of Tata Asset Management Pvt. Ltd. is located at Mulla House, Ground Floor, 51, M.G. Road, Near Flora Fountain, Mumbai – 400 001, Maharashtra. The office hours are Monday to Friday, 9:00 AM to 5:30 PM. For assistance, you can also call (022) 6282 7777 from Monday to Saturday, 9:00 AM to 5:30 PM, or email service@tataamc.com
₹2,000 SIP FAQs
1. Does investing for 25 years always produce better returns than investing for 15 years?
A longer investment period may give contributions more time to compound, which can increase the potential accumulated corpus. However, a longer duration does not guarantee higher returns in every situation. The final value depends on market performance, the timing of returns, and the consistency of investments.
2. Can I withdraw my SIP investment before completing 15, 20, or 25 years?
Yes, investors can generally redeem their mutual fund units before completing the intended investment period, subject to the scheme's terms. However, early withdrawal may result in a lower corpus than projected. Additionally, exit loads may also apply.
3. What happens if I miss a monthly SIP instalment?
The missed contribution will not purchase additional mutual fund units. However, your existing investments will remain invested in the mutual fund scheme and continue to be exposed to market fluctuations.
Disclaimer:
An Investor Education and Awareness Initiative by Tata Mutual Fund.
To know more about KYC documentation requirements and procedure for change of address, phone number, bank details, etc., please visit: https://www.tatamutualfund.com/deshkarenivesh
Please deal only with registered Mutual Funds, details of which can be verified on the SEBI website under ‘Intermediaries / Market infrastructure institutions.’
All complaints regarding Tata Mutual Fund may be directed to service@tataamc.com and/or https://scores.sebi.gov.in/ (SEBI SCORES portal) and/or https://smartodr.in/login
Nomination is advisable for all folios opened by an individual, especially with sole holding, as it facilitates an easy transmission process.
This communication is a part of the investor education and awareness initiative of Tata Mutual Fund.
*Mutual Fund Investments are subject to market risks, please read all scheme related documents carefully.
Author Bio
Ashish Suryakant Pawar
How US Fed Rate Decisions Affect Indian Mutual Funds
Written by Ashish Suryakant Pawar
28 Oct 2026 • 6 minutes read

Get closer to your financial goals
Start InvestingLoading Form...
Loading Similar Blogs...