Asset Allocation by Goal: Why Age Alone May Not Be Enough
Written by Akshay Kumar Rao
13 Aug 2026 • 7 minutes read


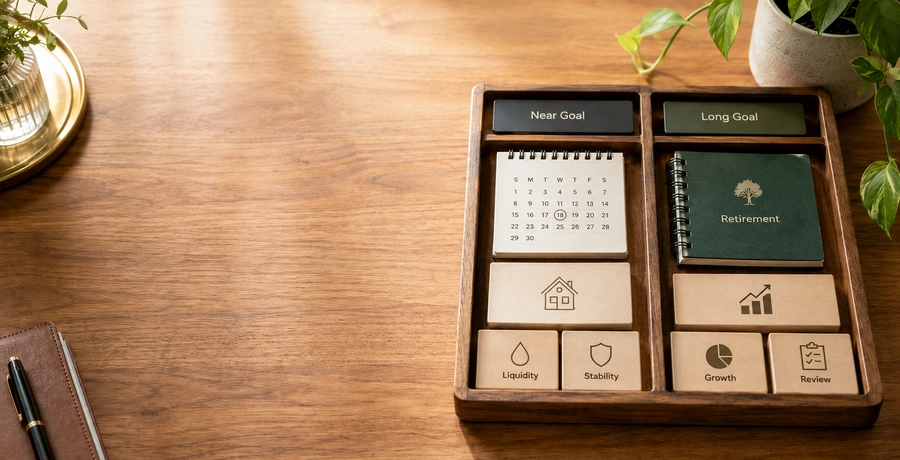
Goal-based asset allocation refers to reviewing investments separately for each financial goal. The focus may not be only on the investor’s age, but also on when the money may be needed, how flexible the goal is, how much risk can be absorbed and how easily the money may need to be accessed.
Using the same asset allocation for both goals may overlook an important question: when might the money be needed?
Age may be one input in asset allocation, but it may not provide a complete picture. Each goal may have a different time horizon, liquidity requirement and ability to absorb market fluctuations. The same investor may therefore have different allocations for different goals.
Table of Content

Why Age Alone May Not Be Enough for Asset Allocation
Age-based thumb rules, such as subtracting one’s age from 100 to arrive at an indicative equity allocation, are sometimes used as simple starting points. However, they may not account for the investor’s complete financial situation.
Two people of the same age may have different incomes, liabilities, dependants, emergency reserves, goal timelines, liquidity needs and abilities to absorb losses.
A simple way to understand asset allocation by goal is to compare two goals with very different timelines.
How Time Horizon Can Change Asset Allocation by Goal?
Goal | Time remaining | Key planning consideration |
Home down payment | 2 years | Limited time to absorb or recover from market fluctuations |
Retirement | 25 years | Longer time horizon and the possible impact of inflation |
The same allocation may not suit both goals. This does not automatically determine which asset class should be used. It simply shows why each goal may need to be evaluated separately.
For the Nearer Goal
Nearer goal: Liquidity and stability may matter more when there is limited time to recover from market movements. The investor may also need easier access to the money when the payment becomes due.
For the Distant Goal
Distant goal: A longer timeline may allow more time to navigate market cycles, while inflation becomes an important consideration. Market-linked exposure may be considered in the context of the investor’s financial situation and ability to absorb losses. Market risk, however, does not disappear with time.
Real-Life Examples of Goal-Based Planning
A home purchase with a flexible date
A couple hopes to make a home down payment in five years, but they can delay the purchase if needed. This flexibility may allow them to evaluate market-linked exposure differently from someone who must make a payment on a fixed date.
A child’s education and a family holiday
Education expenses may be essential and linked to a specific year. A family holiday may be optional or adjustable. Even if both goals are three years away, their importance and flexibility may lead to different planning considerations.
Key Factors That May Influence Goal-Based Asset Allocation
| Input | Question to consider |
| Financial goal | What is the money meant for? |
| Time horizon | When is the money likely to be needed? |
| Goal flexibility | Can the amount or target date be adjusted? |
| Risk capacity | Can a loss be absorbed without affecting the goal? |
| Risk tolerance | How comfortable is the investor with fluctuations in value? |
| Liquidity requirement | How quickly might the money need to be accessed? |
A useful distinction: Risk capacity is the financial ability to absorb a loss. Risk tolerance is the willingness or comfort to experience fluctuations. Both may be relevant.
When Should Goal-Based Asset Allocation Be Reviewed?
An allocation may need to be reviewed:
as the goal date approaches
when income, liabilities or liquidity needs change
when the goal amount or target date changes
after a major life event
when market movements significantly alter the intended allocation
when the ability to absorb losses changes
A review does not necessarily mean that the allocation must change. It is an opportunity to check whether the allocation remains aligned with the goal, the time horizon, liquidity needs and current circumstances.
What Is Rebalancing in Asset Allocation?
Market movements could change the intended allocation. If one asset class increases in value relative to others, it may account for a larger share than originally intended.
Rebalancing generally refers to the process of bringing an allocation closer to its intended mix after market movements or changes in circumstances. The goal timeline, taxation, transaction costs and exit loads, where applicable, may need to be considered.
How to Review Asset Allocation for Each Financial Goal?
Identify each financial goal separately.
Estimate the required amount and target date.
Consider whether the goal is essential or flexible.
Assess the need for liquidity.
Consider the ability and willingness to absorb fluctuations.
Evaluate whether the allocation is aligned with the goal timeline.
Review the allocation periodically and when circumstances change.
Tools That May Help Track Financial Goal Progress
A useful tracker may record the target amount, target date, amount accumulated, regular contribution, current allocation and review date.
| Tool | What it can track | How it may help |
| Simple spreadsheet | Target amount, target date, amount accumulated, contributions and review dates | May offer a customised view without linking financial accounts |
| Goal tracker in an investment platform | Goal value, current value, contributions and broad allocation | May bring investments and goal progress into one dashboard |
| Consolidated Account Statement | Mutual fund holdings and transactions across participating fund houses | May help reconcile holdings before updating a goal tracker |
| SIP or investment calculator | Illustrative contribution, period and assumed rate of return | May help compare scenarios, but the output is illustrative and not assured |
| Calendar reminders | Quarterly, half-yearly or annual review dates | May support a regular review habit without checking too frequently |
| Document folder or digital vault | Goal notes, statements, nomination details and key records | May keep information organised and easier to review |
What to review: target amount, target date, amount accumulated, regular contribution, current allocation, liquidity needs and any material change in the goal or financial situation.
For mutual fund holdings, a Consolidated Account Statement may provide a combined record that can be used to update a separate goal tracker. If a third-party app is used, its data-access permissions, privacy practices, security features and charges may also be reviewed.
Frequently Asked Questions (FAQs)
What is goal-based asset allocation?
Goal-based asset allocation, also called asset allocation by goal, refers to reviewing investments separately for each financial goal based on the goal amount, target date, liquidity need, flexibility, risk capacity and risk tolerance.
Should asset allocation be based only on age?
No. Age may be one input, but asset allocation may also depend on the financial goal, time horizon, liquidity requirement, income stability, liabilities, risk capacity and risk tolerance.
Can one investor have different allocations for different goals?
Yes. One investor may have different asset allocations for different financial goals because each goal may have a different timeline, liquidity need, flexibility and ability to absorb market fluctuations.
Does a long-time horizon make equity safe?
No. A longer horizon may provide more time to navigate market fluctuations, but equity-oriented investments remain subject to market risk.
What is the difference between risk capacity and risk tolerance?
Risk capacity is the financial ability to absorb a loss without affecting a goal. Risk tolerance is the investor’s comfort with fluctuations in investment value. Both may be relevant while reviewing asset allocation.
What is rebalancing?
Rebalancing generally refers to bringing an allocation closer to its intended mix. Taxation, costs and exit loads, where applicable, may need to be considered.
How often should goal progress be reviewed?
The frequency may depend on the goal and the investor’s circumstances. A periodic review may be considered, along with an additional review after a major change in income, liabilities, liquidity needs, goal amount or target date.
What should a goal tracker show?
A goal tracker may show the goal amount, target date, current value, regular contribution, time remaining and review date. It may also record whether the goal is essential or flexible.
Key Takeaways
Age may be one input, but it may not provide a complete picture.
Different financial goals may need to be evaluated separately.
A nearer goal date may leave less time to recover from market fluctuations.
A longer time horizon may not remove market risk.
Liquidity, goal flexibility, risk capacity and risk tolerance may all be relevant.
A simple tracker may help organise goal details and review progress periodically.
*Mutual Fund Investments are subject to market risks, please read all scheme related documents carefully.
Author Bio

Akshay Kumar Rao
Loading Form...
Loading Similar Blogs...